How to Avoid High-Interest Payday Loans? Smart Money Moves
To avoid high-interest payday loans, consider alternatives like credit unions or personal loans. Budgeting and emergency funds can also prevent the need for these costly options.
Navigating the financial landscape requires strategic planning and prudent decision-making, especially when faced with short-term cash flow challenges. High-interest payday loans often appear as a quick fix but can lead to a vicious cycle of debt. Building a solid financial foundation involves establishing a savings plan for unexpected expenses and exploring various lending options.
Credit unions, for instance, offer payday alternative loans (PALs) with significantly lower interest rates. Personal loans from banks or online lenders might also provide more manageable repayment terms. By prioritizing these methods, individuals can maintain financial stability and steer clear of the pitfalls associated with high-cost borrowing. It’s essential to understand the terms of any loan and seek financial advice to make informed decisions that support long-term fiscal health.
The Pitfalls Of Payday Loans
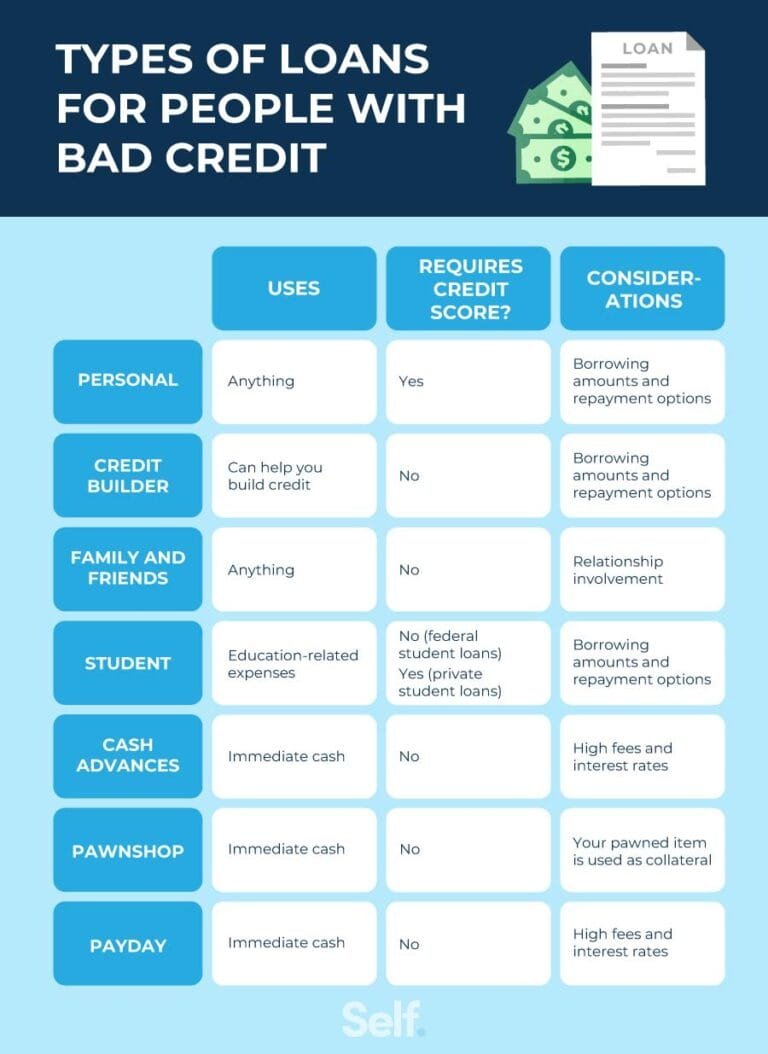
Payday loans might seem like quick fixes for cash shortages. Yet, they come with risks. These loans can turn into financial nightmares. Let’s delve into why these loans might not be the best choice.
Exorbitant Interest Rates
Interest rates on payday loans are sky-high. It’s common to see rates that far exceed standard loans. Consider this: a payday loan could have an annual percentage rate (APR) of 400% or more. That’s significantly higher than most credit cards or personal loans.
With such rates, a small loan can quickly become a huge debt. Always check the APR before borrowing. Look for alternatives with lower interest rates.
Debt Trap Risks
Payday loans can trap borrowers in a cycle of debt. This cycle starts innocently but escalates fast. Borrowers often need another loan to pay off the first. This leads to a dangerous pattern of borrowing and owing.
- Avoid taking out multiple payday loans.
- Explore other options like payment plans.
- Seek financial advice to manage debts wisely.
Remember, payday loans are risky. Always explore other financial solutions first. Your wallet will thank you!

Credit: fastercapital.com
Assessing Your Financial Health
Before you think about payday loans, assess your financial health. This step helps you dodge high-interest traps. Let’s explore how to do this effectively.
Budget Analysis
Creating a budget is your first move. It shows money coming in and going out. Start with listing your income. Then, jot down all expenses. This includes rent, food, and more.
Use a simple table to see it clearly:
| Income | Expenses |
|---|---|
| Job | Rent |
| Side gigs | Food |
| Other | Utilities |
After this, calculate the difference between income and expenses. A positive number means you’re doing well. A negative one shows a need for change.
Identifying Unnecessary Expenses
Look at your expenses again. Find things you can cut. Maybe it’s a gym membership you don’t use. Or daily coffee from a cafe. Cutting these saves you money.
- Cable TV – Do you watch it?
- Gym membership – Is it being used?
- Daily coffee – Make it at home.
Choosing cheaper options works too. Swap dining out for cooking at home. This change keeps more money in your pocket.
By assessing your financial health through budget analysis and identifying unnecessary expenses, you avoid the need for high-interest payday loans. This smart move secures your financial future.
Building An Emergency Fund
An emergency fund acts as a financial safety net. It helps avoid high-interest payday loans during unexpected expenses. Begin by setting a savings goal. This fund covers costs like medical bills or car repairs. Let’s explore simple strategies to build this essential fund.
Starting Small
Begin with what you can afford. Even a small amount makes a difference. Aim for a modest initial target. Think $500 or $1000. This seems more achievable than a large sum. Over time, small contributions can grow into a substantial reserve.
- Set a realistic savings goal
- Save loose change and small bills
- Review and adjust goals as you save more
Automating Savings
Automate transfers to your savings account. Choose a fixed amount. Set it to transfer regularly from your checking account. This happens without manual intervention. It ensures consistent growth of your emergency fund.
- Select a fixed sum for automatic transfer
- Link your checking account to your savings account
- Set a recurring transfer date, like payday
Consistency is key in growing your fund. Remember, an emergency fund secures your finances. It brings peace of mind. Start today, and watch your financial security strengthen.
Exploring Alternative Loan Options
Exploring Alternative Loan Options can save you from the high costs of payday loans. Payday loans often trap borrowers in a cycle of debt. Their sky-high interest rates can lead to a mountain of debt that is tough to escape. It’s vital to consider other avenues for financial help that offer more favorable terms and lower interest rates.
Credit Union Loans
Credit unions are member-owned financial institutions that typically offer lower interest rates on loans than traditional banks. These not-for-profit organizations focus on serving their members rather than maximizing profits. As a result, they can be an excellent source of affordable loans.
- Lower interest rates than most personal loans
- Flexible terms tailored to member needs
- Personalized service with a community focus
Peer-to-peer Lending
Peer-to-peer (P2P) lending platforms connect borrowers directly with investors. These platforms provide an alternative to traditional lending institutions. Borrowers can receive funds quickly, often with less stringent credit requirements than those required by banks.
| Benefits of P2P Lending | Details |
|---|---|
| Competitive rates | Often lower than banks |
| Quick funding | Access to funds within days |
| Accessible online | Easy application process |
Boosting Your Credit Score
Boosting your credit score helps you avoid high-interest payday loans. A good score means better loan options. Let’s learn how to improve it.
Timely Bill Payments
Paying bills on time is key. It shows you’re reliable. Set reminders or use auto-pay. This helps your score grow.
- Set reminders for due dates.
- Use auto-pay features to never miss a payment.
- Pay at least the minimum amount due.
Credit Report Monitoring
Check your credit report often. Spot mistakes early. Fixing them can boost your score. You can check it for free once a year.
- Visit a credit reporting website.
- Request a free credit report.
- Review for any errors.
- Contact the bureau to correct mistakes.
Negotiating With Creditors
Staying clear of high-interest payday loans is crucial for financial health. A smart move is to talk to creditors. Many creditors will work with you to set up a manageable payment plan. This approach can lead to less interest and fees than payday loans.
Setting Up Payment Plans
Open communication with creditors is key. Explain your financial situation. Ask about setting up a payment plan. Most creditors prefer getting paid over time to not getting paid at all. Be honest about what you can afford monthly. Make sure the plan fits your budget.
- Review your bills and income.
- Calculate what you can pay.
- Contact each creditor to negotiate.
- Get the payment plan in writing.
- Stick to the agreed schedule.
Seeking Professional Advice
Seeking help from a credit counselor can be beneficial. These professionals can offer guidance and may help you negotiate with creditors. They can also assist in creating a budget and plan to avoid future debt. Non-profit credit counseling services are often free or low-cost.
| Service | Description | Cost |
|---|---|---|
| Credit Counseling | Professional debt and budget advice | Free or low-cost |
| Debt Management Plan | Structured repayment plan | May have a fee |
| Negotiation Service | Expert creditor negotiation | Varies |
Research local non-profit agencies. Look for accredited counselors. They can help you manage debt effectively.
Educating Yourself On Financial Literacy
Escaping the trap of high-interest payday loans begins with knowledge. Financial literacy empowers you to make smart money choices. Understand budgeting, saving, and borrowing. This knowledge helps you avoid predatory lenders. Start with these steps to boost your financial education.
Utilizing Online Resources
Many websites offer free financial advice. Use these to learn about loans and interest rates. Look for interactive tools like budget planners and loan calculators. These help you see costs clearly. Remember to check reviews. Find trusted sites for the best info.
- Visit government websites for reliable financial data.
- Explore financial blogs and forums for real-life advice.
- Use online courses to deepen your understanding.
Attending Workshops And Seminars
Local workshops and seminars can be gold mines of information. Experts share insights on avoiding debt traps. They also teach money management skills. Check community boards or libraries for event schedules. Most events are free or low-cost.
- Search for local financial education events.
- Join sessions that cover credit and loans.
- Network with professionals who offer personalized tips.
Remember, a little knowledge goes a long way. Equip yourself with financial literacy. Say no to high-interest payday loans for good.

Credit: www.investopedia.com
When You Must Borrow
There comes a time when borrowing money is necessary. Unexpected expenses can hit hard. Quick cash solutions like payday loans tempt with easy access. But, these often come with exorbitant interest rates. This section explores smarter borrowing options.
Borrowing From Friends Or Family
Personal networks can be a safe harbor in financial storms. A loan from friends or family may offer flexible terms and lower costs. Consider the following steps:
- Be open about your situation.
- Agree on clear terms.
- Put it in writing.
- Plan a realistic repayment schedule.
Remember, mixing money and relationships can be tricky. Handle with care to maintain trust.
Using Credit Cards Wisely
Credit cards offer another way to manage short-term expenses. To use them wisely:
- Choose cards with low-interest rates.
- Avoid cash advances.
- Pay more than the minimum due.
- Keep track of your balance.
Smart credit card use can build your credit score. This opens doors to better loan terms in the future.
Legal And Community Resources
Escaping the trap of high-interest payday loans is crucial. Smart financial choices matter. Legal and community resources can help. They offer support and alternatives. Many people overlook these options. Don’t be one of them. Explore every resource available.
Seeking Government Assistance
Government programs can provide relief. They are designed to help those in need. These programs can reduce your expenses. They include food, healthcare, and housing support. Lower expenses mean less need for high-cost loans.
- SNAP helps with food costs.
- Medicaid can cover medical expenses.
- Section 8 assists with housing.
Visit government websites. Apply for programs. Use the benefits instead of payday loans. It’s a smart choice.
Non-profit Organizations
Non-profits can be lifesavers. They offer free financial advice. They provide emergency funds in some cases. Their goal is to support communities.
| Organization | Services | Contact |
|---|---|---|
| National Foundation for Credit Counseling (NFCC) | Debt advice, budgeting help | nfcc.org |
| United Way | Local resources, financial assistance | unitedway.org |
Local churches and charities also assist. They often have funds for those in hard times. Check in your community. Find these groups. Ask for help.
Long-term Financial Planning
Let’s talk about Long-Term Financial Planning. This plan helps you avoid high-interest payday loans. It’s like building a safety net for your money. Want to know how? Keep reading.
Setting Financial Goals
First, let’s set some financial goals. Goals are like your money’s destination. Without them, you’re just wandering. Here’s how to start:
- Identify what you need and want. Needs come first!
- Create a timeline for each goal. Some are near, some are far.
- Break them down into smaller, easier steps.
This makes big goals less scary and more doable.
Consulting With A Financial Planner
Next, let’s talk about consulting a financial planner. Think of them as your money guide. They make plans that fit your life and goals. Here’s why they’re helpful:
- They understand money in ways most of us don’t.
- They can find ways to save you didn’t see.
- They help make a plan that’s right for you.
Talking to a planner can turn your money goals into reality.
Credit: blog.earnipay.com
Frequently Asked Questions
What Are Alternatives To Payday Loans?
Payday loans can be avoided by seeking alternatives such as credit union loans, personal installment loans, or borrowing from friends and family. These options often offer lower interest rates and more flexible repayment terms, making them a safer financial choice.
How Can Budgeting Help Avoid Payday Loans?
Creating a budget helps track expenses, cut unnecessary costs, and save money, reducing the need to rely on high-interest payday loans. A solid budget allows for emergency funds, minimizing the need for short-term borrowing.
Can Negotiating With Creditors Prevent Payday Loan Usage?
Yes, negotiating with creditors for extended payment plans or reduced payments can prevent the need for payday loans. Creditors may be willing to work with you to find a solution that doesn’t involve high-interest borrowing.
Are There Community Programs To Avoid Payday Loans?
Community assistance programs can offer financial help or low-interest loans, helping individuals avoid payday loans. These programs may provide food, bill assistance, or even short-term financial aid to cover urgent expenses.
Conclusion
Navigating financial challenges requires smart strategies. By exploring alternatives to high-interest payday loans, you safeguard your financial health. Embrace budgeting, seek low-interest options, and consider financial advice. Remember, informed choices lead to a stable financial future. Start your journey towards financial freedom today, without falling into the debt trap of payday loans.