How to Lower Your Car Insurance Premium: 12 Ways That Work
Written by Rakib Sarwar, 15 years in banking and lending · Last updated: October 31, 2026
Why trust this guide: every rate figure below comes from NerdWallet’s 2026 rate analysis, Insurance.com (updated July 2026), the Motley Fool citing the Insurance Information Institute, or NAIC consumer guidance. We do not sell insurance.
Disclosure: this page may carry ads or links to insurance partners. They do not affect what we write, and we never recommend a policy because of a commission.
Your renewal notice arrives and the premium is higher again, even though nothing about your driving changed. Before you accept it, know that some of what drives your price is fixed, like your age and state, and some you can change in an afternoon.
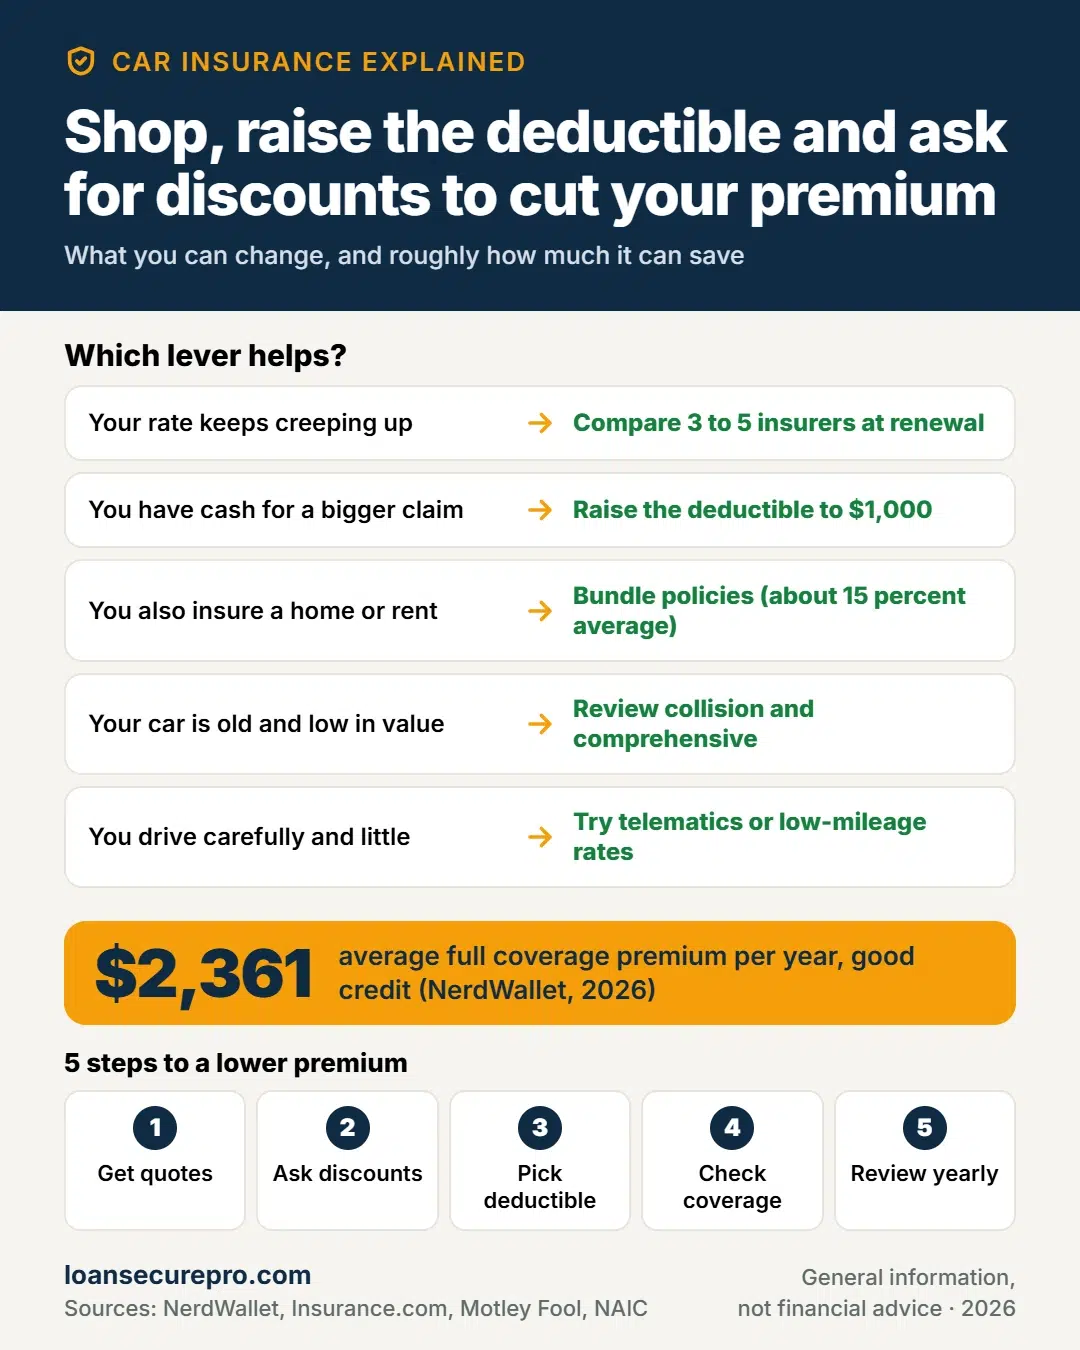
You can lower your car insurance premium by shopping at least three to five insurers, asking for every discount you qualify for, raising your collision and comprehensive deductibles, bundling policies, trying a usage-based program and dropping physical damage coverage on an older car. Keeping a clean record and good credit lowers rates over time, and a safe-driving history is the base for every discount. Most drivers can find savings in under an hour. The right mix depends on how much cash you can spare for a claim, because a lower premium usually means you carry more risk yourself.
In short: get fresh quotes at every renewal, raise the deductible only to an amount you could pay tomorrow, and review whether old cars still need full coverage.
The average driver pays a lot to be wrong about this. NerdWallet’s 2026 rate analysis puts the national average at $2,361 a year for full coverage and $648 for minimum coverage, and rates vary by more than $3,000 between the cheapest and costliest states.
This guide is for US drivers who want a lower bill without leaving themselves exposed. It shows which factors you can and cannot change, gives 12 ways to cut the premium, and works through the break-even math on a higher deductible and on dropping coverage from an old car.
Key takeaways
- Compare quotes from three to five insurers, because prices for the same driver differ widely between companies.
- Raising a deductible from $500 to $1,000 can save a lot, with the Insurance Information Institute figure of 40 percent or more cited for some insurers.
- Bundling home and auto with one carrier saves about 15 percent on average, according to Insurance.com.
- Usage-based programs can discount up to 40 percent for safe driving, but they track how you drive.
- Dropping collision and comprehensive on an old car can lower premiums, but lenders often require both on a financed car.
- A DUI can raise full coverage cost by about 88 percent, and an at-fault accident by about 49 percent, per NerdWallet.
- The cheapest premium is not the best one if it leaves you unable to pay your deductible.
In this guide
- What sets your premium: what you can and cannot change
- 12 ways to lower your premium
- Worked example: raising your deductible
- Worked example: dropping coverage on an old car
- How to cut your premium, step by step
- When to shop and what to expect
- Cheap premium mistakes to avoid
- Where state and insurer rules differ
- Honest limits of this guide
- When to talk to a professional
- Frequently asked questions
What sets your premium: what you can and cannot change
Insurers price on risk, and NerdWallet’s 2026 analysis shows how much each factor moves the number. Some of them are not yours to change, and knowing which saves you from chasing the wrong fix.
| Factor | Annual full coverage (NerdWallet) | Can you change it? |
|---|---|---|
| Age 20 | $4,722 | No, but it falls with age |
| Age 35 | $2,361 | No |
| Age 60 | $2,029 | No |
| Clean record | $2,361 | Yes, over time |
| One speeding ticket | $3,028 (about 28% more) | Yes, it drops off in a few years |
| One at-fault accident | $3,524 (about 49% more) | Yes, it drops off in a few years |
| One DUI | $4,437 (about 88% more) | Slowly, over several years |
| Good credit | $2,361 | Yes |
| Poor credit | $3,954 (about 67% more) | Yes, but slowly |
Insurance.com puts the penalty slightly differently, saying bad credit costs 76 percent more and a speeding ticket raises rates 39 percent on average. The two analyses use different driver profiles, so treat both as ranges, not promises.
Where you live matters most of all. NerdWallet’s median full coverage premium runs from $1,148 a year in Wyoming to $4,296 in Louisiana, and minimum coverage from $192 in Wyoming to $1,597 in New Jersey. You cannot change your state, but you can change everything else on this page.
12 ways to lower your premium
Each lever below has a typical effect and a catch. Start with the free ones, then move to those that shift risk onto you.
| # | Way to save | Typical effect | The catch |
|---|---|---|---|
| 1 | Compare quotes from 3 to 5 insurers | Often the largest single saving | Takes an hour; compare the same coverage limits |
| 2 | Raise collision and comprehensive deductibles | Up to 40% or more at some insurers when moving to $1,000 (III, via Motley Fool) | You pay more per claim |
| 3 | Bundle home or renters with auto | About 15% average on both policies (Insurance.com) | Check the bundled price against separate quotes |
| 4 | Ask for every discount | Multi-car, good student, mature driver, safety equipment and anti-theft devices (NAIC) | Many are not applied unless you ask |
| 5 | Try a usage-based program | Up to 40% for safe driving (Insurance.com) | Tracks speed, braking and mileage; rates may rise for poor scores |
| 6 | Take a defensive driving course | Some insurers discount state-approved courses | Savings vary; confirm before paying |
| 7 | Pay in full or semi-annually | Some insurers discount paying every six months or in full | Needs cash up front |
| 8 | Keep a clean record | A clean record is the base rate in NerdWallet’s table | Takes years to improve |
| 9 | Improve your credit | Good credit pays about 67% less than poor credit (NerdWallet) | Slow, and some states limit credit use |
| 10 | Drop physical damage coverage on an old car | Removes collision and comprehensive premiums | Lenders often require both on financed cars |
| 11 | Choose a cheaper car to insure | Costly-to-repair cars and some SUVs cost more (NAIC) | Get quotes before you buy |
| 12 | Review the policy yearly | Fix wrong address, mileage, drivers or vehicle details | Wrong details can void a claim, not only raise a bill |
Two of these deserve more space. The first is the deductible, because it is the single lever that trades premium for risk directly, and our guide to how car insurance deductibles work covers it in depth.
The second is physical damage coverage on old cars. Comprehensive covers theft, fire, flood and glass, as we explain in what comprehensive car insurance covers, and dropping it removes that protection entirely.
Worked example: raising your deductible
A higher deductible lowers your premium because you cover more of each small claim. The break-even question is how many claim-free years it takes for the savings to cover the extra risk.
The result depends on how often you claim and how large the premium gap is. Ask your insurer for both quotes before you decide.
The Motley Fool, citing the Insurance Information Institute, says raising a deductible to $1,000 could save drivers 40 percent or more with some insurers. That is the upper end, and the $140 above is only 18 percent of $780.
A practical rule: raise the deductible only to an amount you could pay from savings tomorrow. A $1,000 deductible you cannot cover is not a saving, it is a claim you cannot afford to file.
Worked example: dropping coverage on an old car
Collision and comprehensive pay up to the car’s market value, minus the deductible. As the car loses value, the most they can pay shrinks, while the premium may not.
When one year of premium is a large share of the car’s value, the coverage costs more than it is likely to return. If you could replace the car from savings, dropping physical damage coverage can be sensible.
NAIC guidance says to consider reducing or dropping physical damage coverage on older vehicles unless a lienholder requires it. If you still owe money on the car, check your loan agreement first, since most lenders require both coverages.
How to cut your premium, step by step
Do these in order. Each takes less time than the last, and the early ones usually save the most.
- Find your current policy. Pull your declarations page and note your limits, deductibles, mileage and listed drivers and cars.
- Fix wrong details. Check the address, vehicle, birth dates and annual mileage. NAIC says to verify that your policy information is accurate.
- Get three to five quotes. Request the same limits and deductibles from each insurer so you compare like for like.
- Ask for every discount. Name them: multi-car, good student, mature driver, safety equipment, anti-theft, paid in full, paperless.
- Test two deductibles. Ask for quotes at $500 and $1,000, then use the break-even math above.
- Price a bundle. Add home or renters insurance and see if the combined price is lower than separate policies.
- Review old cars. Compare the premium for collision and comprehensive with the car’s value.
- Switch or negotiate. Move to the best quote or ask your current insurer to match it, and cancel the old policy only after the new one starts.
Information to have ready: declarations page, driver’s license numbers for all drivers, vehicle identification numbers, current mileage, and the dates of any tickets or accidents.
When to shop and what to expect
Insurance.com advises keeping a policy at least six months before shopping so you qualify for continuous-coverage discounts. After that, shop at each renewal and after any big life change.
| When | Why it matters | What to do |
|---|---|---|
| Every renewal | Rates drift, and a new quote can beat your renewal price | Get three to five quotes a month before it renews |
| After a ticket or accident ages off | Records drop off after three to five years | Ask for a rate review or shop |
| After a move | Rates vary by where you park the car | Update the address and get new quotes |
| When mileage drops | Low mileage can lower rates | Report new annual mileage |
| Before buying a car | Some models cost far more to insure | Get quotes on the exact model |
Switching is usually painless. You buy the new policy first, confirm the start date, and then cancel the old one, so there is no gap in coverage.
Cheap premium mistakes to avoid
A low price can hide a bad deal. Four mistakes come up again and again.
Cutting liability limits. Lower limits save little and expose your savings in a serious crash. Cut physical damage coverage instead.
Comparing different coverage. A quote with a higher deductible or lower limits looks cheaper because it covers less. Always compare identical coverage.
Filing tiny claims. Insurance.com notes that claims can raise your rates for several years, so avoid small claims you can pay out of pocket.
Lying on the application. Wrong garaging address or hidden drivers can lead to denied claims or canceled policies. Accuracy matters more than a lower first quote.
Do
- Compare identical limits and deductibles
- Ask which discounts you qualify for
- Keep an emergency fund for your deductible
- Re-shop at every renewal
- Check your loan terms before dropping coverage
Don’t
- Drop liability to save money
- Pick a deductible you could not pay
- Cancel the old policy before the new one starts
- Misstate mileage, drivers or address
- File small claims you can pay yourself
Where state and insurer rules differ
Auto insurance is regulated state by state, so the best saving move differs by location.
Rate levels. NerdWallet’s median full coverage premium ranges from $1,148 in Wyoming to $4,296 in Louisiana, so your starting point depends heavily on your state.
Minimum coverage. State minimums vary. Minimum coverage costs from $192 in Wyoming to $1,597 in New Jersey, and the minimum required limits differ too.
Credit and other factors. Some states limit how insurers use credit or other rating factors. If your credit is weak, ask whether your state restricts its use.
Discounts. The discounts offered, and the amounts, differ by insurer and state. Ask for the full list in writing.
Honest limits of this guide
This guide explains common ways to lower a premium. Your price depends on your insurer, state, vehicle and record, so the figures here are averages from the sources named, not quotes for you.
NerdWallet’s figures are national averages for sample drivers with a $1,000 deductible, and the page’s date label is inconsistent, so we call them 2026 figures. The NAIC page’s tips are timeless, but the dollar figure on it dates from 2001, so we did not use it.
The dollar examples use assumed premiums and values. We did not request quotes from any insurer, and usage-based programs and bundling savings differ widely.
When to talk to a professional
A licensed independent agent can quote several insurers at once, which saves time. Ask one before you switch if your situation is unusual, such as a high-risk record or a classic car.
Talk to your state Department of Insurance if you think you were unfairly rated or denied coverage. Talk to your lender before dropping any coverage on a financed or leased car.
Disclaimer: this article is general information, not insurance, legal or financial advice. Coverage and prices depend on your policy, your state and your insurer. Confirm details with a licensed professional before relying on them.
Frequently asked questions
What is the fastest way to lower my car insurance premium?
Compare quotes from three to five insurers using the same coverage and deductibles. Prices for the same driver differ widely between companies, and this takes about an hour. Then ask for every discount you qualify for and test a higher deductible if you can afford the extra risk.
How much does raising my deductible save?
It varies. The Motley Fool, citing the Insurance Information Institute, says raising a deductible to $1,000 could save 40 percent or more with some insurers. Many drivers save less, so request quotes at two deductibles and compare the yearly difference against the extra amount you would pay per claim.
Does bundling home and auto insurance save money?
Often. Insurance.com says insuring home and auto with one carrier can save about 15 percent on average on both policies. That is an average, so compare the bundled price against separate quotes from other insurers, because a bundle is not always the cheapest option for you.
Will a usage-based program lower my rate?
It can. Insurance.com says some carriers discount just for signing up and up to 40 percent for safe driving. These programs monitor speed, braking and mileage through an app or device, and in some cases poor scores raise your rate, so read the terms first.
Should I drop collision and comprehensive on an old car?
Possibly. NAIC says to consider reducing or dropping physical damage coverage on older vehicles unless a lienholder requires it. Compare one year of premium with the car’s value. If you could replace the car from savings, dropping it may make sense. Keep it if you have a loan.
How long does a ticket or accident affect my rate?
Usually three to five years, after which it drops off your record for rating, according to the Motley Fool. The increase is largest at first. NerdWallet puts the full coverage cost at about 28 percent higher after a speeding ticket and 49 percent after an at-fault accident.
Does my credit affect my car insurance rate?
In most states, yes. NerdWallet shows full coverage at $2,361 a year with good credit versus $3,954 with poor credit, about 67 percent more. Insurance.com says 76 percent more on average. Some states restrict credit use, so ask your insurer how it applies where you live.
How often should I shop for car insurance?
At least once a year, a month or so before renewal, and after major changes such as a move, a new car or a ticket aging off. Insurance.com advises keeping a policy for six months before shopping to qualify for continuous-coverage discounts.
Is the cheapest policy the best choice?
Not always. A cheaper quote may carry lower limits, a higher deductible or fewer coverages. Compare identical coverage first, then judge service and claims handling. Make sure your deductible is an amount you could actually pay. The lowest price loses its value if you cannot afford to use the policy.
Can I lower my premium without switching insurers?
Yes. Ask your current insurer to review your discounts, correct wrong details on your policy, test a higher deductible, bundle policies or enroll in a usage-based program. Showing a lower competing quote sometimes prompts a match. If it does not, switching is simple when you start the new policy first.
The bottom line
The most reliable ways to lower your car insurance premium are to compare three to five quotes, ask for every discount, bundle if the price is lower, and raise your deductible only to an amount you could pay. Review old cars for physical damage coverage you may no longer need.
Today, pull your declarations page and request two quotes at different deductibles. Do the break-even math from this guide, and put a reminder in your calendar to shop again a month before your next renewal.
Sources
- NerdWallet: Average cost of car insurance (2026 rate analysis) (accessed Oct 31, 2026)
- Insurance.com: Top ways to save on car insurance (updated July 6, 2026) (accessed Oct 31, 2026)
- The Motley Fool: 9 proven ways to slash your car insurance premium (Nov 12, 2024) (accessed Oct 31, 2026)
- NAIC: Tips for saving on your auto insurance (accessed Oct 31, 2026)
One Comment