Car Insurance for a New Car: What You Need Before You Drive Home
Written by Rakib Sarwar, 15 years in banking and lending · Last updated: October 31, 2026
Why trust this guide: every rule and figure below comes from NerdWallet (updated July 2026), ValuePenguin (July 2026), CarInsurance.com (June 2026), Compare.com (March 2026) or Kelley Blue Book, with the date stated where one is given. We do not sell insurance.
Disclosure: this page may carry ads or links to insurance partners. They do not affect what we write, and we never recommend a policy because of a commission.
You found the car, agreed on a price, and the dealer is asking for proof of insurance before handing over the keys. If you have never insured a new vehicle, or you are adding a second car, the order of steps matters more than you might expect.
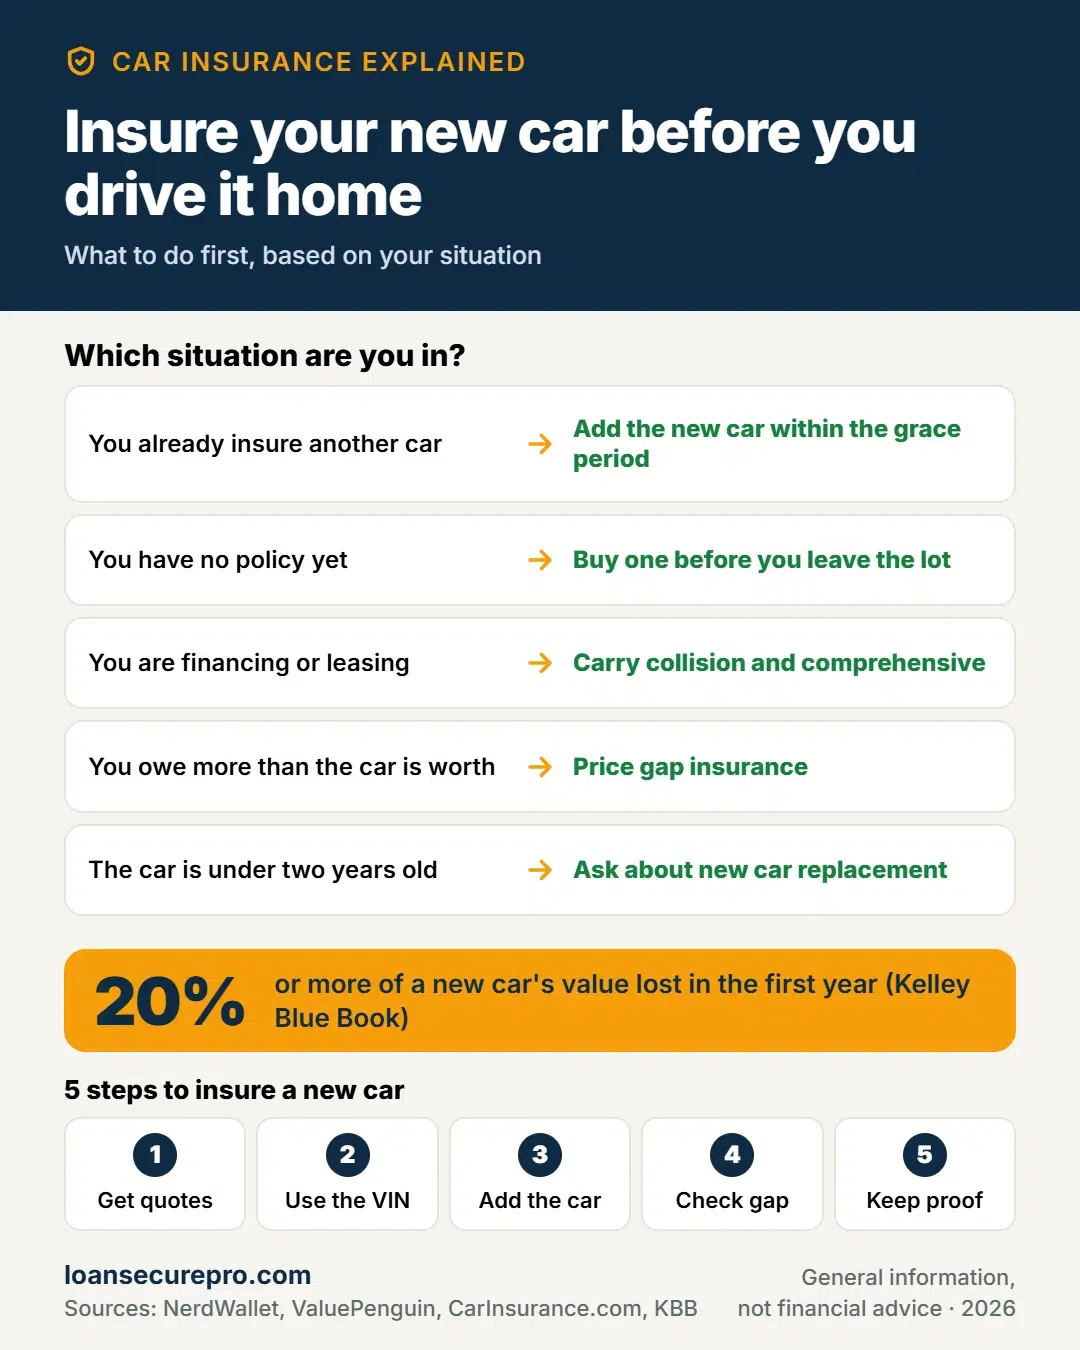
You need car insurance in place before you drive a new car home. If you already have a policy, it usually extends to the new car for a grace period of about 7 to 30 days, but you must add the car officially. If you finance or lease, the lender will require collision and comprehensive coverage and often gap insurance. Expect a higher premium than for an older car, about 10 percent more in one comparison and 65 percent more in another. New cars lose about 20 percent of their value in year one, so gap and replacement coverage are worth pricing.
In short: get quotes before you buy, have proof of coverage at the dealership, add the car to your policy the same day, and decide on gap coverage before you sign the loan.
Most problems come from timing. A grace period that seems generous can end the day an accident happens, and a policy that covers your old car may not cover the new one at the same level.
This guide is for US drivers buying or leasing a new vehicle. It explains when you need coverage, what lenders require, how gap and new car replacement coverage work, and why a new car costs more to insure. It then works through the dollar math on a first-year total loss.
Key takeaways
- You need insurance before you drive a new car off the lot, and you cannot back-date a policy afterwards.
- An existing policy usually carries over for about 7 to 30 days, but only if you add the car before the grace period ends.
- Lenders and leasing companies usually require collision and comprehensive coverage.
- Gap insurance pays the difference between what you owe and what the car is worth, and costs a few dollars a month according to the Insurance Information Institute.
- New car replacement coverage is not offered by every insurer, and Geico, Progressive and State Farm do not offer it.
- New cars cost more to insure, from about 10 percent to 65 percent more depending on the comparison.
- Comparing quotes before you buy is the easiest way to avoid a surprise premium.
In this guide
- When you need insurance on a new car
- What lenders and lessors require
- Gap and new car replacement coverage
- Why a new car costs more to insure
- Worked example: a first-year total loss
- How to insure a new car, step by step
- New car insurance mistakes to avoid
- Where state and insurer rules differ
- Honest limits of this guide
- When to talk to a professional
- Frequently asked questions
When you need insurance on a new car
NerdWallet’s July 2026 guide says you need insurance before you buy the car, because you must have it before driving off the lot. ValuePenguin adds that you cannot back-date insurance to apply retroactively.
What you must do depends on whether you already have a policy. The table lays out the common cases.
| Your situation | What happens | What to do |
|---|---|---|
| No policy at all | You need coverage before you drive home | Get quotes with the VIN, make and model, then buy a policy |
| Insuring another car with the same company | Coverage usually extends to the new car for a grace period | Add the car to the policy as soon as you buy it |
| Switching insurers | The new insurer needs a policy in place before you drive | Start the new policy on the purchase date |
| Only liability on your old car | The new car may be uncovered for damage to itself | Add collision and comprehensive before you drive |
| Cash purchase | State minimums are required by law | Consider full coverage on a car this valuable |
Compare.com says most insurers give at least a week to add a new car, and ValuePenguin puts the typical grace period at about 7 to 30 days, with Progressive giving 30 days and some others under a week. Check your own policy for the exact number.
Grace-period coverage generally follows your current policy’s limits. ValuePenguin says it covers the new car up to the cash value of your old car, which can be far less than the price of the new one.
What lenders and lessors require
If you finance or lease, the lender or leasing company has a say in your coverage. NerdWallet says a loan or lease will likely require full coverage, which is not a separate policy type but a combination of state minimums with comprehensive and collision.
Collision covers crash damage, as we explain in our guide to what collision car insurance covers. Comprehensive covers non-collision damage such as theft, hail, fire and vandalism. Both pay up to the car’s market value minus your deductible.
| Coverage | Who requires it | What it does |
|---|---|---|
| Liability | Every state | Pays for injuries and damage you cause to others |
| Collision | Lenders and lessors | Repairs or replaces your car after a crash |
| Comprehensive | Lenders and lessors | Covers theft, fire, hail and vandalism |
| Gap insurance | Often leasing companies, sometimes lenders | Pays the loan balance above the car’s value |
| Uninsured motorist and PIP | Some states | Protects you from uninsured drivers and covers medical costs |
Compare.com says a cash buyer needs only state-minimum coverage, though optional coverages are available. NerdWallet recommends buying more than your state’s minimum, because a new car’s repair cost can pass a minimum policy quickly.
The deductible you choose changes the premium and what you pay per claim, and our guide to how car insurance deductibles work explains how to pick one.
Gap and new car replacement coverage
Two optional add-ons target the main risk with a new car: it loses value faster than you pay the loan down.
Gap insurance. NerdWallet says a loan or lease typically requires gap insurance, though no state requires it to drive. It covers the difference between your remaining balance and the car’s market value if the car is totaled or stolen. The Insurance Information Institute says it generally costs a few dollars a month.
New car replacement. This pays to replace your car with the same make and model, minus your deductible. Standard collision and comprehensive pay only actual cash value, so without replacement coverage you would buy the replacement yourself.
| Feature | Gap insurance | New car replacement |
|---|---|---|
| What it pays | The loan or lease balance above the car’s value | A new car of the same make and model |
| Who benefits | Anyone who owes more than the car is worth | Owners of cars in their first years |
| Typical cost | A few dollars a month (III) | About 5 to 13 percent added to comprehensive and collision (Farmers) |
| Availability | Widely offered, also through lenders | Not universal; Geico, Progressive and State Farm do not offer it |
| Time limit | Until the balance drops below the car’s value | Insurer limits, such as under 2 years or 15,000 miles |
NerdWallet’s table of insurers shows how limited replacement coverage is. Allstate requires a car two model years old or newer, Liberty Mutual and Safeco require under one year old and under 15,000 miles, and Shelter includes it on all its policies. That article dates from September 2023, so confirm current terms.
Why a new car costs more to insure
CarInsurance.com says a new car is almost always more expensive to insure than a used one, with classic and exotic cars as the exception. Three reasons stand out.
First, replacement value is higher, so insurers face bigger payouts. Second, newer cars have costlier parts and technology, which raises repair bills. Third, used cars have already lost value, which lowers the insurer’s exposure.
| Comparison | Result | Source |
|---|---|---|
| Allstate, 2023 model vs 2014 model | $3,549 vs $2,148, about 65% more | CarInsurance.com, 2026 |
| Allstate, 2023 model vs 2020 model | About 24% more | CarInsurance.com, 2026 |
| Nationwide, pickups | About 10% more | CarInsurance.com, 2026 |
| New vs four-year-old Honda Civic, full coverage | About 10% more | ValuePenguin, 2026 |
The gap between the sources shows how much depends on the insurer and the car. CarInsurance.com used a 40-year-old driver with a clean record and full coverage, while ValuePenguin’s comparison used one model in one state, so treat both as examples, not forecasts.
Two things can pull the price back down. CarInsurance.com says most insurers offer a new-car discount, around 7 percent for vehicles three years old or newer. ValuePenguin says safety features such as lane assist, backup cameras and blind-spot warning can reduce the premium increase.
For more ways to cut the bill, see our guide on how to lower your car insurance premium.
Worked example: a first-year total loss
The scenario that gap insurance targets is simple: the car is totaled in the first year while you still owe more than it is worth. Kelley Blue Book says many vehicles lose about 20 percent or more of their value in the first year.
NerdWallet gives a similar example. On a $30,000 loan for a car worth $25,000 with a $500 deductible, collision pays $24,500 and the driver owes $5,500 without gap coverage, and only the $500 deductible with it.
Now add new car replacement. In ValuePenguin’s example, a buyer paid $25,000 and the car was worth $20,000 when totaled, so replacement coverage adds the $5,000 difference. In our example above, the difference between the $35,000 price and the $28,000 value is $7,000.
Whether that trade is worth it depends on your savings. If a $2,500 or $7,000 shortfall would hurt, the add-ons are cheap protection, and if you could absorb it easily, you may skip them.
How to insure a new car, step by step
- Decide the exact car. Note the year, make, model and trim, since the price depends on all four.
- Get quotes before you buy. You can quote with the make and model, and finalize with the VIN and mileage.
- Match your lender’s rules. Ask what coverage and maximum deductible the lender requires on the loan or lease.
- Price gap and replacement. Ask for quotes with and without each add-on and compare the yearly cost.
- Start the policy on purchase day. Policies cannot be back-dated, so set the start date to the day you take the car.
- Bring proof of insurance. Show your insurance card, which you can usually download from the app or website.
- Add the car if you have a policy. Do this the same day, not at the end of the grace period.
- Remove the old car when it is sold. Update the policy so you do not pay for a car you no longer own.
Information to have ready: the VIN, current mileage, the lender’s name and address, each driver’s date of birth and license number, and how you will use the car.
NerdWallet warns that buying insurance through the dealership can be a poor choice because of upselling and because you lose the chance to compare quotes. Get your own quotes first.
New car insurance mistakes to avoid
Four mistakes cost new owners the most. Each is easy to avoid.
Waiting until the end of the grace period. A claim before you add the car can be denied, as Compare.com notes. Add it on day one.
Assuming an old liability-only policy covers the new car. If your old car only had liability, the new car may have no cover for damage to itself until you add collision and comprehensive.
Skipping gap on a small down payment. A new car loses about a fifth of its value in year one, so a small down payment leaves you owing more than the car is worth.
Buying coverage at the dealership by default. Compare at least three insurers, because pricing for the same car varies widely.
Do
- Get quotes with the VIN before you buy
- Start coverage on the purchase date
- Ask about gap and replacement coverage
- Ask about new-car and safety discounts
- Keep your proof of insurance in your phone
Don’t
- Drive home before coverage is active
- Rely on the full grace period
- Cancel the old policy before the new one starts
- Buy the cheapest limits just to match the lender
- Let a lapse in coverage happen
Where state and insurer rules differ
Auto insurance is regulated state by state, and each company writes its own grace-period and add-on rules, so the details differ.
Minimum coverage. NerdWallet says every state requires liability insurance, and uninsured and underinsured motorist coverage is required in nearly half of states. Some states require PIP or no-fault coverage.
Grace periods. They run from under a week at some insurers to 30 days at Progressive, per ValuePenguin. Not every insurer extends coverage, so check your policy.
Replacement coverage. NerdWallet says new car replacement is not universal and may not be available in every state where an insurer offers it.
Dealer and lender rules. Dealers and lenders set their own insurance paperwork and deductible limits, so ask before you sign.
Honest limits of this guide
This guide explains how coverage for a new car generally works. It cannot tell you what your policy says or what your lender requires, and your rate depends on your state, record and vehicle.
The cost figures are examples from CarInsurance.com and ValuePenguin that used different drivers and cars. They are not quotes, and we did not request quotes from any insurer.
The first-year value loss is a Kelley Blue Book average, and the loan balance in the worked example is an assumption. NerdWallet’s replacement-coverage article is from 2023, so insurer eligibility rules may have changed.
When to talk to a professional
An independent agent can quote several insurers at once and explain your lender’s coverage requirements. Ask one before you finalize a loan, especially if your down payment is small.
Talk to your lender before you drop or change coverage on a financed car. Contact your state Department of Insurance if a claim is denied and you think it should have been paid.
Disclaimer: this article is general information, not insurance, legal or financial advice. Coverage and prices depend on your policy, your state and your insurer. Confirm details with a licensed professional before relying on them.
Frequently asked questions
Do I need insurance before I buy a new car?
Yes. NerdWallet says you need insurance in place before you drive the car off the lot, and ValuePenguin says you cannot back-date a policy. If you already have a policy you can show the dealer your card, but you still need to add the new car officially.
How long do I have to add a new car to my policy?
It depends on the insurer. ValuePenguin says grace periods typically run about 7 to 30 days, with Progressive giving 30 days and some insurers under a week. Compare.com says most give at least a week. Check your policy, and add the car on the day you buy it.
Does my old policy cover my new car right away?
Usually for a short time. Your current coverage generally extends to the new car for the grace period, up to the cash value of your old car, according to ValuePenguin. If your old policy only has liability, the new car may not have cover for damage to itself, so add the right coverage first.
What coverage does a lender require on a new car?
NerdWallet says a loan or lease will likely require full coverage, meaning state minimum liability plus comprehensive and collision. Leasing companies sometimes also require gap insurance. Ask your lender for its exact requirements and any limit on the deductible before you buy.
What is gap insurance, and do I need it?
Gap insurance pays the difference between your loan or lease balance and the car’s market value if it is totaled or stolen. No state requires it, but leases often do. It is most useful with a small down payment or long loan. The Insurance Information Institute says it generally costs a few dollars a month.
What is new car replacement coverage?
It pays to replace your car with the same make and model, minus your deductible, if it is totaled. Standard coverage pays only actual cash value. NerdWallet says it is not universal, and Geico, Progressive and State Farm do not offer it. Eligibility limits are often one to five years or 15,000 miles.
Is insurance more expensive for a new car?
Usually. CarInsurance.com found a 2023 model cost 65 percent more than a 2014 model with Allstate and 24 percent more than a 2020 model. ValuePenguin found about 10 percent more for a new Civic than a four-year-old one. Newer cars cost more to repair and replace.
Can I buy a new car with only state-minimum insurance?
If you pay cash, yes, because only state minimum coverage is required by law, per Compare.com. If you finance or lease, the lender will require more. Even with cash, minimum liability does not pay to repair your own car, so many owners choose collision and comprehensive.
Do new car discounts exist?
Yes. CarInsurance.com says most insurers offer a new-car discount of around 7 percent for vehicles three years old or newer. Safety features such as lane assist, backup cameras and blind-spot warning can also reduce the increase, according to ValuePenguin. Ask your insurer which discounts apply to your model.
Should I buy insurance through the dealership?
Usually not first. NerdWallet warns that dealership insurance can mean upselling and that you lose the chance to compare quotes. Get quotes from at least three insurers before you shop for the car, then bring proof of coverage to the dealer.
The bottom line
Insure a new car before you drive it home, add it to your policy the day you buy it, and match what your lender requires. Price gap and new car replacement coverage, because a new car loses about a fifth of its value in the first year.
Before you sign, get three quotes with the VIN, ask your lender for its coverage and deductible rules, and decide on gap coverage using the math in this guide. Then put the car on your policy on purchase day.
Sources
- NerdWallet: New car insurance, when you need it and how to get it (updated July 6, 2026) (accessed Oct 31, 2026)
- ValuePenguin: New car insurance (updated July 7, 2026) (accessed Oct 31, 2026)
- CarInsurance.com: New vs. used car insurance (updated June 18, 2026) (accessed Oct 31, 2026)
- Compare.com: How soon do you need to insure a new car? (updated March 2, 2026) (accessed Oct 31, 2026)
- NerdWallet: New car replacement insurance explained (Sept 28, 2023) (accessed Oct 31, 2026)
- Kelley Blue Book: How to beat car depreciation (modified Nov 6, 2025) (accessed Oct 31, 2026)